
Fast Track Summary
-
Arithmetic vs. Geometric Disconnect: High average annual returns often mask severe compound erosion caused by variance drag in volatile, multi-asset portfolios.
-
Math of Rebalancing Frequencies: Over-rebalancing generates friction through capital gains taxes and transaction costs, while under-rebalancing allows asset drift to amplify downside volatility.
-
Tailored Execution Matters: High-net-worth portfolios require opportunistic, rebalancing-band strategies rather than rigid calendar schedules to capture volatility harvest.
Multi-Asset Volatility Drag: Why Rebalancing Frequencies Determine Long-Term Portfolio Compound Rates
A tech executive holds a concentrated portfolio that generates a 20% gain in Year 1, suffers a 20% loss in Year 2, and climbs 20% in Year 3. On paper, the average annual return reads as a positive 6.67%. In reality, the portfolio’s actual value has dropped. An initial $10,000,000 allocation sits at $9,600,000.
This disconnect between average arithmetic returns and actual compound growth is the invisible tax known as volatility drag. For affluent investors, managing this geometric decay is not an academic exercise—it is the foundation of long-term wealth preservation.
Volatility drag represents the mathematical loss in compound portfolio growth caused by variance in annual returns. Because negative percentage losses require larger percentage gains to break even, higher portfolio variance depresses the actual geometric return below the simple arithmetic average, degrading real capital accumulation over time.
The mathematical dynamic driving this loss rests on the fundamental relationship between arithmetic and geometric mean returns. A close approximation of this behavior can be expressed through the variance drag formula:
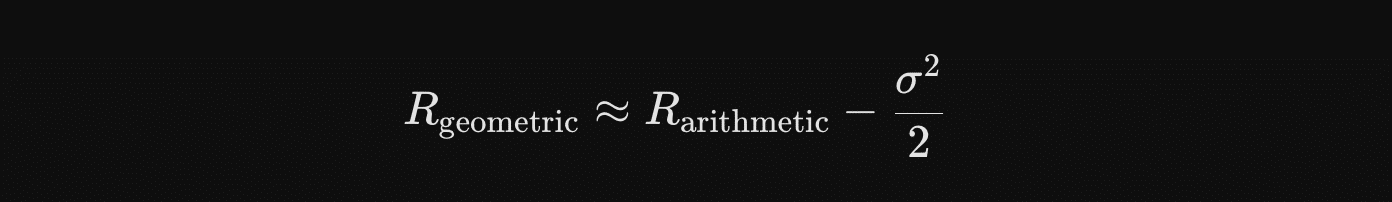
In this equation, represents the actual compound rate of growth, is the simple average return, and is the portfolio variance. As annual returns fluctuate wildly, variance increases, creating a wider gap between expected performance and actual wealth retention.
When managing high-net-worth wealth, relying solely on unadjusted market averages creates a false sense of security. Strategic asset allocation relies on deliberate structure to minimize variance drag across diverse market environments.
Evaluating how annual return variance depresses capital over time demonstrates the severe cumulative impact of unmanaged swings on an initial baseline return:
-
Zero Volatility Environment: At 0% annual variance (), an 8.0% arithmetic return yields an exact 8.00% real geometric growth rate, resulting in 0.00% compound loss.
-
Low Volatility Environment: At 10% annual variance (), an 8.0% arithmetic return yields a 7.95% real geometric growth rate, creating a modest 0.05% annual compound loss.
-
Moderate Volatility Environment: At 20% annual variance (), an 8.0% arithmetic return yields a 7.80% real geometric growth rate, resulting in a 0.20% annual compound loss.
-
High Volatility Environment: At 30% annual variance (), an 8.0% arithmetic return yields a 7.55% real geometric growth rate, creating a 0.45% annual compound loss.
-
Extreme Volatility Environment: At 40% annual variance (), an 8.0% arithmetic return yields a 7.20% real geometric growth rate, causing a substantial 0.80% annual compound loss.
How Rebalancing Frequency Directly Impacts Compound Growth Rates
Optimal rebalancing frequencies mitigate volatility drag by resetting portfolio weights back to baseline targets, systematically buying underperforming assets low and selling appreciated assets high. This systematic approach captures the volatility harvest while preventing asset drift from exposing the total portfolio to unmanaged tail risks.
The primary tool for controlling portfolio variance is disciplined rebalancing. However, selecting a rebalancing schedule involves navigating a clear trade-off between mathematical precision and real-world friction.
Conventional wealth management often defaults to rigid quarterly or annual calendar rebalancing. While calendar intervals reduce administrative overhead, they frequently misalign with actual market behavior. Rebalancing too frequently incurs unnecessary realization of capital gains, triggering federal and state tax burdens that outweigh the mathematical benefits of variance reduction.
Conversely, rebalancing too infrequently exposes high-net-worth investors to severe asset drift. During prolonged bull markets, high-volatility growth assets expand to dominate total portfolio weighting. This unmanaged growth transforms a balanced risk profile into an equity-heavy allocation, leaving capital vulnerable to sharp drawdowns.
Evaluating execution cadences highlights the primary trade-offs between precision control and real-world drag:
-
High-Frequency Execution (Daily or Weekly): Delivers maximum variance control and optimal theoretical alignment, but introduces extreme drag through short-term capital gains taxes, transaction friction, and administrative tracking overhead.
-
Fixed Calendar Execution (Quarterly or Annual): Offers simple implementation and predictable operations, but exposes capital to unmanaged asset drift between intervals and ignores major market moves that fall between calendar dates.
-
Opportunistic Tolerance Bands (Rebalancing Triggers): Maximizes the volatility harvest by systematically buying dips and selling rallies, but requires ongoing active monitoring and quantitative tracking mechanics.
High-income professionals navigating complex holdings must balance portfolio movements with underlying tax implications. The Internal Revenue Service taxes realized short-term capital gains at standard income rates, making excessive rebalancing within taxable accounts counterproductive.
Advanced portfolio execution shifts the focus from rigid calendar dates toward dynamic opportunistic rebalancing bands. By establishing upper and lower tolerance thresholds around asset classes—such as a +/- 5% band around a core 30% international equity allocation—investors rebalance based on structural market movements rather than artificial dates.
This approach minimizes tax drag while systematically capturing the rebalancing bonus: buying underperforming assets at depressed valuations and selling extended holdings before market turnarounds.
To protect multi-generational assets from systemic downturns, wealth strategies require multi-layered tax planning to shield capital realignments from excessive taxation.
Case Scenario: Managing Drift in High-Yield and Concentrated Equities
Consider a business owner who sold an enterprise and deployed $20,000,000 across a multi-asset allocation. Over three years, high-yield alternative credit and tech equities experienced significant divergence. The tech segment surged by 65%, while credit instruments traded sideways due to interest rate shifts.
An unmanaged approach would allow equities to drift from 40% to nearly 65% of total wealth. When market conditions reversed, the inflated equity position exposed the entire portfolio to a 30% drawdown, eroding years of wealth generation.
By applying dynamic tolerance bands, the advisor systematically rebalanced capital out of equities near market highs into discounted debt instruments. This disciplined realignment locked in gains, insulated core principal, and maintained stable yield across economic cycles.
Implementing precise allocation mechanics requires tailored oversight. To explore how custom structural mandates preserve capital across market movements, evaluate our approach to comprehensive wealth management.
Counterintuitive Insights and Overlooked Risks in Multi-Asset Allocations
A common misconception in wealth management suggests that adding more non-correlated assets always improves long-term portfolio returns. While diversification lowers overall portfolio variance, adding low-yielding, high-volatility assets solely for non-correlation can depress total compound wealth faster than variance reduction can save it.
Another major overlooked risk is the interaction between systematic withdrawal rates and volatility drag during retirement. Retirees taking fixed distributions from volatile portfolios risk experiencing sequence-of-returns decay through a cascading operational risk chain:
-
Market Downturn Event: Sharp drawdowns depress the broad portfolio valuation, reducing the underlying capital base.
-
Forced Asset Liquidation: Systematic cash distributions force the sale of depreciated assets at depressed valuations to meet income needs.
-
Capital Base Depletion: Liquidation permanently shrinks the pool of compounding assets remaining inside the portfolio structure.
-
Reduced Recovery Capacity: The smaller remaining capital base cannot fully capture subsequent market rebounds, permanently lowering long-term wealth trajectories.
-
Accelerated Volatility Friction: Ongoing drawdowns combined with fixed withdrawals lock in permanent capital losses and accelerate portfolio exhaustion.
Furthermore, asset location plays a critical role in mitigating volatility drag. Executing frequent rebalancing inside taxable accounts introduces substantial drag through tax realization. Taxable rebalancing must leverage opportunistic cash flows, dividend distributions, and strategic tax-loss harvesting to realign positions without incurring preventable capital gains taxes.
High-net-worth families require holistic structures that integrate portfolio risk controls with legacy objectives. Strategic realignment across complex estates should incorporate robust estate planning frameworks to pass wealth efficiently across generations.
Strategic Execution Framework for High-Net-Worth Portfolios
Managing portfolio volatility requires a systematic framework designed to optimize long-term geometric returns:
-
Define precise allocation targets: Establish clear long-term benchmarks based on specific cash flow needs, liquidity constraints, and multi-generational goals.
-
Implement dynamic tolerance bands: Replace rigid calendar rebalancing schedules with quantitative thresholds (e.g., relative 10% to 20% shifts from baseline target weights) to optimize trade execution.
-
Optimize asset location for tax efficiency: Place high-turnover, high-yield, and volatile asset classes within tax-advantaged accounts while reserving tax-efficient equity strategies for taxable accounts.
-
Harvest losses systematically: Combine portfolio realignments with tax-loss harvesting to offset realized capital gains with harvested losses.
-
Integrate organic cash flow rebalancing: Utilize incoming interest, dividends, and business distributions to fund underweight positions without triggering asset sales.
By removing emotion from portfolio execution, high-net-worth investors can effectively reduce variance drag and maximize the real compound growth rate of their wealth over time.
Key Takeaways
-
Arithmetic Averages Mislead: High average annual returns do not guarantee long-term wealth accumulation due to the compounding drag caused by asset volatility.
-
Math of Variance Drag: Portfolio compound growth tracks the geometric mean, which deteriorates as volatility increases relative to arithmetic returns.
-
Calendar Rebalancing Limitations: Fixed schedule rebalancing often creates unnecessary tax drag or allows excessive asset drift during trending market environments.
-
Tolerance Bands Win: Opportunistic rebalancing based on defined percentage thresholds optimizes the volatility harvest while managing execution costs.
-
Location Drives Net Returns: Structuring rebalancing mechanics across taxable and tax-deferred accounts protects portfolio growth from unnecessary friction.
Partner with KDH Financial
Managing multi-asset portfolios across changing tax environments demands continuous analytical precision and tailored execution. At KDH Financial, we partner with executives, business owners, and affluent families to design customized, tax-efficient strategies that protect capital against market drag. Contact our team today through our Contact Us page to review your allocation framework and optimize your long-term compound growth strategy.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute individualized financial, legal, investment, or tax advice. While KDH Financial strives to deliver accurate and up-to-date insights, market conditions, regulatory frameworks, and tax laws change rapidly, and strategies must be evaluated against your specific financial circumstances. You should consult with qualified wealth managers, certified financial planners, tax advisors, or legal professionals before implementing any working capital formulas, cash management frameworks, or financial strategies discussed herein. Past performance and liquidity modeling are not guarantees of future results, and KDH Financial assumes no liability for decisions made based on the content of this publication.



